


Canada moves to unlock $1 trillion in new investment
Canada is moving to make investment a central pillar of its economic strategy, combining tax changes, faster project approvals and new infrastructure initiatives as Prime Minister Mark Carney targets $1 trillion in investment over five years.
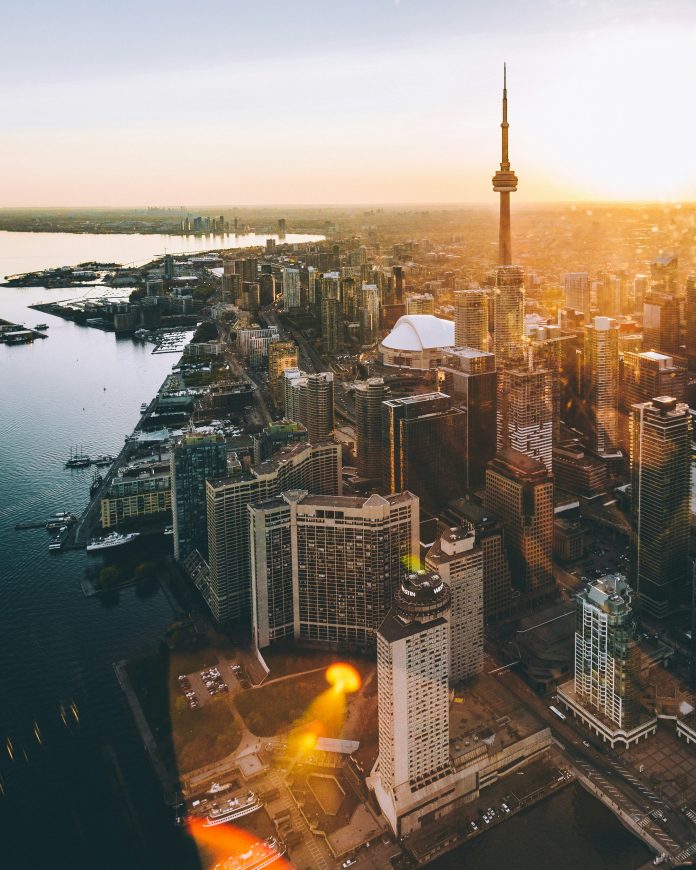
The first Canada Investment Summit, held in Toronto on September 14–15, brought together investors from nearly 30 countries managing more than $100 trillion in assets. According to the Office of the Prime Minister, the summit resulted in nearly $500 billion in new investment commitments for Canada.
The government is seeking to build on that momentum by lowering the cost of new investment. At the summit, Carney announced the Productivity Mega Deduction, expanding immediate expensing to more than 65% of capital assets, compared with roughly 15% previously. Eligible investments include mining property, pipelines, fibre-optic infrastructure, software, research and development, computer equipment, rail, bridges and roads.
The Office of the Prime Minister says the measure will reduce Canada’s marginal effective tax rate on new business investment from about 13% to 6.4%, less than half the comparable U.S. rate. Immediate expensing will also become permanent, allowing businesses to recover eligible investment costs sooner.
The new incentive builds on measures introduced in Budget 2025, which included a Productivity Super-Deduction covering eligible machinery, equipment and technology. The government has also reduced taxes on income, capital gains and new business investment, according to the Prime Minister’s Office.
Tax competitiveness is being matched by an effort to bring more capital into major projects. Since September 2025, 27 nation-building initiatives have been referred to Canada’s Major Projects Office, representing approximately $500 billion in potential private investment, the Prime Minister’s Office says.
Energy, critical minerals, artificial intelligence and defence are among the sectors being targeted. The government has committed approximately $140 million through the Canada Growth Fund to support the Marathon critical-minerals project in Ontario, while the Business Development Bank of Canada is deploying new financing for Canadian defence and dual-use technology companies.
The summit also highlighted the role of institutional capital. Canada’s pension funds, insurers and other institutional investors announced nearly $100 billion in new capital for Canadian assets, while the country’s major banks committed nearly $325 billion in new financing for Canadian businesses and infrastructure, according to the Prime Minister’s Office.
One of the largest individual announcements came from Bell Canada and the Government of Saskatchewan, which announced a $52.5 billion AI infrastructure hub with 1.2 gigawatts of capacity. The project is expected to create more than 4,500 jobs and represents the largest investment in Saskatchewan’s history.
Canada is also seeking to use existing infrastructure to attract additional private capital. The government plans to pursue long-term concessions for the operation of the country’s four largest airports while retaining public ownership of the underlying land and assets. The Prime Minister’s Office says capital raised could be reinvested in regional airports, transportation infrastructure and a national broadband backbone.
For Carney, the investment proposition extends beyond individual incentives or projects. The Prime Minister’s Office points to Canada’s critical-mineral reserves, energy resources, skilled workforce, AAA credit rating and lowest net debt-to-GDP ratio in the G7, alongside preferential trade access to 1.5 billion consumers across 51 countries.
The government is also seeking to reduce the time required to bring major projects to market. Carney has said Canada can maintain high regulatory standards while moving towards a “one project, one review, one year” approach for major developments.
The strategy is therefore built around a combination of lower investment costs, access to resources and markets, infrastructure and faster project delivery. The immediate objective is to turn the commitments announced in Toronto into projects and productive capacity across the Canadian economy.
As Carney told investors at the summit, “Canada is building big. Build with us.”


