Thursday, September 10, 2026
No menu items!
Home Blog

Global FDI rebounds to $1.6 trillion, but investment remains concentrated

Global FDI rebounds to $1.6 trillion, but investment remains concentrated

Global foreign direct investment returned to growth in 2025, reaching $1.6 trillion after two consecutive years of decline. But the recovery was far from evenly distributed, with developed economies and a handful of strategic industries capturing much of the increase.

The World Investment Report 2026, published by UN Trade and Development (UNCTAD), shows that global FDI rose 6% last year. Investment into developed economies increased 11% to $723 billion, while flows to developing economies grew by only 2%, reaching $901 billion.

The figures point to a changing investment landscape in which the destination and nature of capital are becoming as important as the overall volume. Increasingly, investors are favouring large-scale projects tied to technology, energy and industries considered critical to future economic growth.

Developing markets see mixed results

Developing Asia remained the largest recipient among developing regions, attracting $644 billion in 2025.

Latin America and the Caribbean recorded stronger growth, with investment rising 14% to $188 billion.

Africa received about $70 billion. While that was below the exceptional level reached in 2024, the amount remained roughly one-third above the region’s average for 2010–2024.

The least developed countries recorded a 21% increase in inflows to $43 billion. Yet their share of global FDI remained just 2.7%, with investment concentrated in a relatively small number of largely resource-rich economies.

The distribution of investment was similarly concentrated at the global level.

The world’s 20 largest host economies attracted more than 80% of total FDI in 2025.

Technology is changing where capital is going

The strongest growth was concentrated in projects connected to strategic industries.

According to the report, artificial intelligence infrastructure, semiconductors, critical minerals and energy-transition technologies and services together accounted for 44% of global greenfield project values in 2025. Five years earlier, those sectors represented only 16%.

Data centres were the standout driver, generating $235 billion in announced greenfield investment and international project finance values. Oil and gas followed with $38 billion, while semiconductor projects increased by $13 billion.

Other parts of the investment landscape were considerably weaker. Project values declined by $37 billion in renewable energy, $55 billion in infrastructure and $55 billion in global-value-chain-intensive industries.

The result is a recovery that looks strong in aggregate but is considerably narrower when examined by sector.

More investment does not automatically mean more development

For developing economies, attracting foreign capital is only part of the challenge. Its wider economic value depends on whether projects create productive capacity, jobs, skills and opportunities for technology transfer.

The report found that low-income and lower-middle-income economies attracted only around 10% of strategic-sector investment between 2020 and 2025, compared with more than 20% in other sectors.

That imbalance could become more significant as international investment shifts towards projects requiring substantial capital, advanced technology and specialised skills.

For countries seeking to compete for these investments, the report highlights the importance of dependable infrastructure, workforce development, stronger domestic suppliers and access to regional markets.

Governments increasingly shape investment flows

Governments are also taking a more active role in determining where international capital is directed.

A record 229 investment policy measures were introduced worldwide in 2025. Most remained favourable to investors, but many were designed to attract capital into strategic industries, support domestic economic priorities or respond to concerns over economic security.

That shift is likely to make competition for major investment projects more intense, particularly in sectors linked to technology, energy and industrial development.

2026 outlook remains uncertain

The global investment recovery is entering 2026 against a difficult economic and geopolitical backdrop.

Trade-policy uncertainty, geopolitical tensions, conflicts, high financing costs and increasing economic fragmentation continue to create risks for companies considering cross-border investment.

At the same time, governments are competing more aggressively for projects that could strengthen technological capabilities and establish new sources of long-term growth.

The findings are expected to feed into discussions at the World Investment Forum 2026, which will take place in Doha, Qatar, from 25 to 27 October. Governments, investors and development partners will examine how the increasingly selective investment environment can produce broader economic benefits.

The latest figures suggest that global investment is recovering, but the quality and distribution of that recovery matter. For developing economies, the challenge is no longer simply to attract capital, but to turn it into investment that expands productive capacity and creates opportunities across the wider economy.
Saudi PIF Creates New Company to Develop 20-Sq-Km Gulf Coast Destination

Saudi PIF Creates New Company to Develop 20-Sq-Km Gulf Coast Destination

Iran Opens 95 MW Solar Project as Government Targets Faster Renewable Expansion

0

Iran Opens 95 MW Solar Project as Government Targets Faster Renewable Expansion

Iran has commissioned a 95 MW solar project in Tehran Province, strengthening renewable power supply for one of the country’s largest industrial zones as the government seeks to expand clean-energy generation.

Iran has brought 95 MW of new solar capacity into operation at Shamsabad Industrial Town in Tehran Province, adding generation capacity close to a major concentration of manufacturing activity.

President Masoud Pezeshkian attended the inauguration on August 25, according to the Iranian Presidency. The project comprises the 63 MW Qaed Shahid and 32 MW Shahday-e Lamerd solar plants, both located at Shamsabad Industrial Town.

The project was developed on a 147-hectare site and was completed in less than nine months, according to Iran’s official IRNA news agency, which reported that more than 6 trillion rials was invested in its construction.

Its location is closely linked to industrial electricity demand. IRNA reported that the facility is expected to provide part of the electricity required by Shamsabad Industrial Town during daytime peak-consumption periods. Hamidreza Azimi, deputy head of Iran’s Renewable Energy and Energy Efficiency Organization (SATBA), said the objective is to use renewable generation to supply industrial users in the area and reduce the extent of electricity interruptions affecting them.

Solar capacity accelerates

The commissioning comes as Iran’s solar sector expands rapidly.

IRNA reported that the country’s installed solar-generation capacity reached nearly 5,500 MW following the Shamsabad project.

The Iranian government is pursuing a substantially larger expansion. President Pezeshkian has set a target of 30,000 MW of clean and renewable generation capacity within two years, according to the Presidency.

SATBA’s Azimi separately said the organisation is targeting 12,000 MW of renewable capacity by March 2027, with solar accounting for approximately 11,000 MW of that total. He also said the Shamsabad project was financed through resources from Iran’s National Development Fund, which has provided financing support for renewable-energy projects.

The difference between the two figures is important: the 30,000 MW figure is the broader government target, while the 12,000 MW target cited by SATBA relates to the nearer-term renewable-capacity objective.

Industry becomes a focus for solar investment

The Shamsabad project also illustrates a shift towards locating renewable generation closer to electricity-intensive economic activity.

According to IRNA, the facility’s primary purpose is to support electricity supply to the industrial town, while SATBA has said that expanding renewable capacity around industrial areas is intended to help minimise interruptions to industrial power consumption.

The approach is particularly relevant as Iran seeks to address the imbalance between electricity supply and demand without relying solely on additional conventional generation.

Tehran Province is already seeing a broader expansion of solar projects. Tehran Governor Mohammad Sadegh Motamedian told the Iranian Presidency that solar capacity in the province had increased from 23 MW before the Pezeshkian administration took office to 400 MW, representing a 20-fold increase.

The governor also said the province is pursuing smaller and decentralised solar projects alongside large facilities, including installations at schools, mosques, agricultural sites, municipalities and industrial towns.

Financing and domestic production

The government’s renewable-energy push is also creating demand for financing and domestic equipment production.

SATBA’s Azimi said the Shamsabad project was financed through the National Development Fund, while noting that the fund has increased its support for renewable-energy projects over the past year.

The Iranian Presidency has separately reported Pezeshkian’s emphasis on supporting domestic solar-panel manufacturers, linking renewable-energy expansion with the development of local production capabilities.

For Iran’s energy sector, the Shamsabad project therefore represents a combination of two priorities: adding renewable generation and directing that capacity towards industrial electricity demand.

The immediate 95 MW addition is modest compared with the government’s longer-term targets, but the project demonstrates the model being pursued-developing solar generation close to major consumers while using public financing and domestic investment to accelerate deployment.

If Iran succeeds in scaling the programme towards its stated targets, the investment opportunity will extend beyond solar generation itself to equipment manufacturing, project development, financing, grid infrastructure and distributed renewable systems.

Azerbaijan-Uzbekistan Investment Pipeline Outgrows $500 Million Fund

Azerbaijan-Uzbekistan Investment Pipeline Outgrows $500 Million Fund

Azerbaijan and Uzbekistan are preparing to expand their bilateral investment mechanism as the scale of projects under development increasingly exceeds the capacity of their existing $500 million fund.

Azerbaijan and Uzbekistan are looking to increase the financial capacity supporting their investment partnership as a growing pipeline of projects extends across tourism, industry, energy, mining, agriculture, finance and construction.

The issue emerged during the third meeting of the Supreme Interstate Council in Tashkent on August 23, where Azerbaijani President Ilham Aliyev and Uzbek President Shavkat Mirziyoyev reviewed the countries’ expanding economic cooperation.

The Azerbaijan-Uzbekistan Investment Company (AUIC) was established in 2023 with initial committed capital of $500 million, according to the investment company’s own information. The vehicle was created to make direct investments in businesses and projects in Azerbaijan and Uzbekistan.

President Aliyev said approximately $160 million of the fund’s capital has already been allocated and indicated that the remaining resources would be deployed as additional investment opportunities are identified. He also described the bilateral fund as particularly effective among Azerbaijan’s investment cooperation mechanisms with other countries.

The bigger issue, however, is the size of the pipeline now emerging between the two economies.

Aliyev said the value of projects already planned or contracted is significantly greater than the fund’s original capitalisation. He cited around $5 billion in planned investment in Uzbekistan’s tourism sector alone, while hotel and residential developments in Tashkent are being implemented outside the AUIC framework.

That suggests the next stage of bilateral investment cooperation could involve a larger capital base as well as financing arrangements beyond the existing fund.

Investment pipeline broadens

The latest projects demonstrate how the relationship is expanding beyond conventional trade.

According to Azerbaijan’s presidential administration, projects inaugurated or launched during the August 23 visit included Davr Bank, following its acquisition by the International Bank of Azerbaijan; a gypsum plant operated by Matanat-A; and two STEAM schools established by Landau Education Group.

The new investment programme also includes five SOCAR filling stations, the Sea Breeze Uzbekistan residential and recreational complex being developed by Agalarov Development, and the Baku City residential project by TuranAZ.

Mining and agriculture are also represented, with the countries launching a silver ore processing and concentration project under the Sur Gold and Silver Project, as well as plans for new fruit orchards by Gold Fresh Fruits, according to the Azerbaijani presidency.

The breadth of these projects reflects a progressively more diversified investment relationship, covering financial services, education, real estate, energy infrastructure, mineral processing and agriculture.

Industrial cooperation takes centre stage

For Uzbekistan, industrial development is expected to remain a major area of cooperation.

President Mirziyoyev said businesses from the two countries are already working on projects involving geology, energy, chemicals, finance, construction and agriculture. He called for the faster deployment of the joint investment company’s existing capital and said the fund should subsequently be expanded.

The two countries are also setting a higher target for bilateral commerce. Mirziyoyev said trade between Azerbaijan and Uzbekistan has tripled over the past five years, while the overall portfolio of joint projects has exceeded $5 billion. The two governments have set $1 billion in bilateral trade as their next target.

The AUIC has already been building a diversified portfolio. Its published investment strategy identifies areas including financial services, transport, energy, healthcare, logistics, manufacturing, pharmaceuticals, fintech, information technology and education.

The company has also reported investments in Uzbekistan’s higher-education, technology and retail sectors during 2026, including $2 million in the American University of Technology in Tashkent, $1.7 million in a data-centre equipment venture with Engineering+, and $15 million in a local retail chain.

A larger financing role

The emerging picture is therefore broader than an expansion of a single investment fund. Azerbaijan and Uzbekistan are building a wider economic partnership in which government-backed capital can sit alongside corporate investment and potentially attract additional financing.

Transport is another component of the relationship, with the two sides discussing cooperation around the Middle Corridor and plans for a joint Caspian Sea fleet, according to Mirziyoyev’s remarks at the council meeting.

The two countries are also pursuing cooperation in geological exploration. The Azerbaijani authorities have previously announced plans involving AzerGold, Uzbekgeologorazvedka and the AUIC, adding natural-resource development to the investment agenda.

For investors, the significance of the latest developments lies in the growing gap between the size of the original $500 million investment vehicle and the much larger portfolio of projects now being discussed or implemented.

If the fund is expanded as proposed, the move would give Azerbaijan and Uzbekistan a larger institutional platform for directing capital into cross-border projects while potentially creating more opportunities for private and international investors to participate in the next phase of the partnership.

France, Saudi Arabia Expand Economic Ties as Investment Grows

France, Saudi Arabia Expand Economic Ties as Investment Grows

French foreign direct investment stock in Saudi Arabia reached €16.3 billion in 2024, as France and the Kingdom use the latest high-level visit to broaden economic cooperation and encourage greater two-way investment.

France and Saudi Arabia are expanding their economic partnership, with French foreign direct investment stock in the Kingdom reaching €16.3 billion ($19 billion) in 2024, more than doubling over five years and making France the fourth-largest source of foreign direct investment in Saudi Arabia.

The figure was presented by Saudi Investment Minister Fahad bin Abduljalil Al-Saif at the French-Saudi Investment Roundtable in Paris on August 24, held during the official visit of Saudi Crown Prince and Prime Minister Mohammed bin Salman. French investors currently hold 651 investment licences across 18 sectors in the Kingdom.

The investment figures highlight the scale of an economic relationship that the two governments are seeking to broaden. While French investment remains strongly linked to established industries, opportunities are expanding into energy, financial services, digital infrastructure, advanced manufacturing, transport and logistics, gaming and tourism, according to the Saudi Investment Ministry briefing presented at the roundtable.

The Paris meeting brought together government officials, business leaders and chief executives from both countries. The Saudi Press Agency said discussions covered energy, industry, financial services, transport and logistics, healthcare, culture, tourism and artificial intelligence, with the two sides examining joint projects and further private-sector cooperation.

Investment becomes more reciprocal

The relationship is also developing beyond French capital entering Saudi Arabia. France and Saudi Arabia have agreed to strengthen economic ties and cross-investments, while increasing cooperation between financial institutions and insurance and financing organisations, according to the joint statement issued after the leaders’ meeting.

A major example is the planned development by Qiddiya Investment Company of a mixed-use, multi-park destination at Cergy-Pontoise in France’s Île-de-France region. The project is expected to combine entertainment, leisure, hospitality, culture and sport, with investment of around €6 billion over its development lifecycle, according to the French-Saudi joint statement.

The two governments are also establishing a financing framework to support projects delivered by French companies in Saudi Arabia. Separately, Saudi Arabia’s Ministry of Finance and Bpifrance Assurance Export signed a statement establishing a credit line of up to $5 billion to finance or refinance contracts involving French companies in the Kingdom.

The financing mechanism could provide additional support for French companies seeking to participate in Saudi projects as the Kingdom continues to attract international expertise and capital under its economic diversification programme.

Technology and industry broaden the relationship

The latest talks indicate that the bilateral economic relationship is becoming broader in sectoral terms. France and Saudi Arabia agreed to deepen cooperation in artificial intelligence, quantum computing, emerging technologies and capacity building, according to the joint statement.

For French companies, Saudi Arabia is already an important market across a range of industries. France’s Ministry for Europe and Foreign Affairs identifies urban and high-speed rail, tourism, agriculture, healthcare, renewable energy, civil nuclear energy and defence among the principal areas of opportunity, while also highlighting prospects for smaller French companies in consumer goods, agrifood and telecommunications equipment.

The industrial component remains significant. Around 60% of French investment stock in Saudi Arabia is concentrated in manufacturing, according to the investment briefing, although French companies are increasingly pursuing opportunities in emerging sectors linked to Vision 2030.

Trade provides another link

Investment is developing alongside a substantial trade relationship. The French-Saudi joint statement said bilateral trade reached approximately $11.8 billion in 2025. France Diplomatie’s latest published economic data, which is based on an earlier reporting period, records €10.7 billion in bilateral goods trade, with French exports reaching €4 billion.

Saudi Arabia is also continuing to attract foreign capital more broadly. Al-Saif said foreign direct investment inflows reached approximately €6.1 billion in the first quarter of 2026, up 2.4% year on year, according to figures presented at the Paris roundtable.

The wider economic relationship is being supported by a more formal strategic framework. During the latest visit, Macron and Mohammed bin Salman chaired the first meeting of the French-Saudi Strategic Partnership Council, which launched new initiatives aimed at strengthening cooperation between the two countries.

The two sides also agreed to extend their cooperation on AlUla through 2035, continuing collaboration in archaeology, heritage and culture, while further agreements and memoranda covered areas including defence, healthcare, artificial intelligence, emerging technologies and entertainment. The Élysée said more than 22 agreements and memoranda of understanding were announced in connection with the visit.

For France, the €16.3 billion stock of investment already established in Saudi Arabia provides an existing platform for companies to pursue new opportunities in the Kingdom. For Saudi Arabia, greater investment in France offers another channel for deploying capital and building commercial links in Europe.

The latest visit therefore adds new investment projects, financing mechanisms and areas of cooperation to an economic relationship that is already substantial. With both governments seeking greater cross-investment and broader private-sector participation, the next stage will depend on how effectively the agreements announced in Paris translate into projects and long-term commercial activity.

Argentina’s LNG Expansion Takes a US$51 Billion Step Forward

Argentina’s LNG Expansion Takes a US$51 Billion Step Forward

Argentina’s plans to build a large-scale LNG export industry have moved into a new stage, with the Argentina LNG project applying for inclusion in the country’s Large Investment Incentive Regime (RIGI) as its project partners advance plans for a potential final investment decision later this year.

The development, led by state-controlled YPF with Italy’s Eni and XRG, the international investment arm of Abu Dhabi National Oil Company (ADNOC), represents a projected US$51 billion investment over the life of the project, according to YPF. The company describes it as the largest private investment proposed in Argentina and the largest project submitted under RIGI to date.

The project is designed to connect Argentina’s Vaca Muerta gas resources in Neuquén with LNG export infrastructure on the Atlantic coast of Río Negro, creating an integrated chain from upstream production to international markets.

A major infrastructure build-out

The investment required by the initial development is expected to reach approximately US$29 billion by 2031, the targeted start-up date for the first LNG facilities.

Around US$24 billion of that amount is planned for infrastructure, including industrial facilities, dedicated gas transportation and port infrastructure. A further US$5 billion is expected to be directed towards upstream development and drilling.

The project will include gas production in Neuquén, transportation infrastructure, processing facilities and liquids-fractionation trains before the gas reaches the liquefaction units offshore Río Negro. YPF’s project plan calls for two floating LNG units with combined capacity of 12 million tonnes per annum (mtpa).

From Vaca Muerta to LNG exports

The development is intended to give Argentina a new route to monetise its substantial unconventional gas resources.

Vaca Muerta is the upstream foundation of the project, with production in Neuquén supplying the gas required for the planned LNG facilities. The export component will be located offshore in the Gulf of San Matías, linking the country’s major shale-gas resource with international LNG markets.

YPF’s project materials indicate that the development has the potential to reach 18 mtpa of LNG capacity as it expands beyond the initial two-unit configuration.

For Argentina, the significance extends beyond the LNG facilities themselves. Increasing gas production and export capacity would create an additional source of foreign-exchange earnings while opening a larger international market for Vaca Muerta output.

RIGI provides the investment framework

The application for RIGI is intended to establish a more predictable regulatory and financial framework for a project requiring substantial upfront capital and long-term international financing.

The regime provides qualifying large-scale investments with stability covering areas including taxation, customs, foreign exchange and legal conditions. YPF has said those provisions are important to attracting the international investment and financing needed for Argentina LNG.

The application is therefore an important development milestone, but it does not represent a final commitment of the full US$51 billion. The project still has to progress through its technical, commercial and financing stages before construction can proceed at full scale.

International partnership

The project’s international structure has developed over several stages. YPF and Eni initially advanced Argentina LNG before XRG joined the development. The three companies signed a Joint Development Agreement in February 2026, while subsequent agreements have expanded the partnership’s role in the upstream segment.

The combination of Argentina’s gas resources with the international experience and investment capabilities of Eni and XRG is intended to support the project’s development and eventual access to global LNG markets.

Export and employment potential

The project partners estimate that Argentina LNG could generate approximately US$10 billion in annual export revenues over two decades once operational.

Construction is also expected to create significant demand for workers and local suppliers. Project estimates indicate that construction activity could generate around 20,000 jobs annually between 2026 and 2030, with employment potentially reaching 40,000 at the peak of the build-out.

The opportunities would extend across drilling, engineering, pipeline construction, processing, port services, logistics and other parts of the energy supply chain.

FID remains the next major milestone

The project partners are targeting a final investment decision in the second half of 2026, with the first two FLNG units planned to begin operations in 2031.

The period ahead will be critical as the project moves from regulatory approval and development planning towards financing and execution. Its progress will also provide an important test of Argentina’s ability to convert Vaca Muerta’s resource base into large-scale export infrastructure.

If completed as planned, Argentina LNG would establish a new connection between the country’s unconventional gas production in Neuquén and global LNG markets, while positioning LNG exports as a potentially significant new component of Argentina’s energy economy.

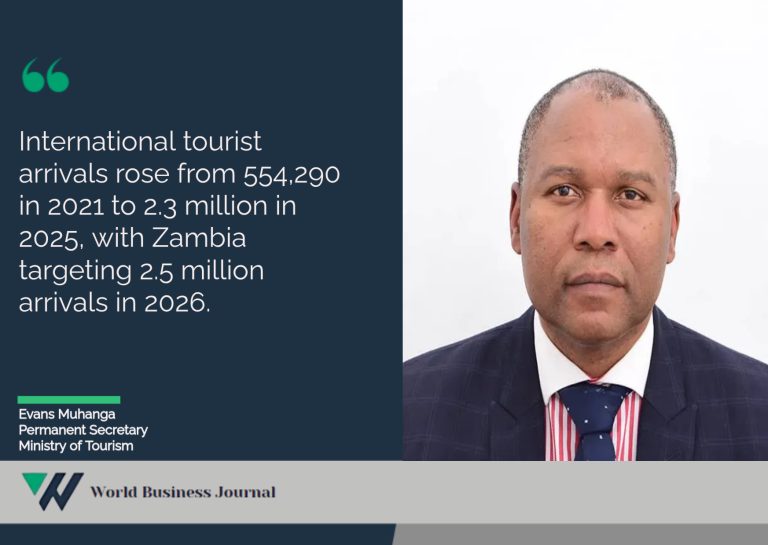
Zambia Tourism Arrivals Rise to 2.3 Million as Evans Muhanga Details Sector Recovery and Investment

Zambia Tourism Arrivals Rise to 2.3 Million as Evans Muhanga Details Sector Recovery and Investment

World Business Journal talks to Evans Muhanga, Permanent Secretary at Zambia’s Ministry of Tourism, about the recovery of the country’s tourism sector, the policies driving visitor growth, and the challenges and opportunities shaping its next phase. He discusses visa reforms, infrastructure, domestic tourism, digital marketing and the outlook for tourism investment.

What are the current figures for international tourist arrivals, and which source markets are driving growth most strongly?

International tourist arrivals rose from 554,290 in 2021 to 2.3 million in 2025, with Zambia targeting 2.5 million arrivals in 2026. The USA is now the leading source market, with 61,586 arrivals, followed by China with 55,008. The United Kingdom, previously Zambia’s largest source market, ranked third in 2025 with 40,290 arrivals.

In Africa, regional markets remain important, particularly Zimbabwe, Tanzania and the Democratic Republic of Congo (DRC). Growth has been driven largely by stronger destination marketing and promotion.

Which government intervention has had the greatest impact in unlocking Zambia’s tourism potential?

A key intervention has been the relaxation of Zambia’s visa regime, with more than 167 countries now eligible for visa-free entry.

The policy has reduced barriers for international travellers, making it easier to book flights, enter Zambia and visit the country with fewer administrative requirements.

How has tourism revenue performed in recent years, and what is driving changes in average spend per visitor?

Tourism contributed about US$700 million in 2025, and the sector is targeting US$1 billion in 2026. Through the development of a Tourism Satellite Account, the government aims to capture tourism’s wider economic impact, including spending on transport, airport services, restaurants, accommodation and other visitor services.

Non-tax revenue collected by the Ministry increased from K131 million in 2021 to K473 million in 2025, while total tourism-related revenue streams grew from K485 million in 2021 to K2.8 billion in 2025.

A key factor has been the digitisation of payment systems through the Government Service Bus and ZamPortal, supported by the Smart Zambia Institute, making it easier for businesses and international visitors to access and pay for government services.

Average visitor stays have also increased from three to four days to around five to seven days, indicating higher visitor spending during trips.

What concrete improvements have been made to tourism access and air connectivity, and what impact are they having on accessibility?

The length of tourism access roads rehabilitated has increased from 1,600 km in 2021 to more than 2,500 km, while loop roads have improved from 556 km to more than 1,270 km.

Working with partners, we have maintained 16 airstrips in protected areas and continued periodic maintenance. We have also upgraded provincial aerodromes, including Kasama and Mansa, while plans are underway for Nakonde Airport, alongside upgrades to Solwezi, Kalumbila and Mfuwe. The private sector has also contributed to runway development and expansion projects, including at Royal Zambezi Airstrip.

Despite these improvements, the infrastructure gap remains significant. Several tourism sites remain difficult to access because of inadequate roads and supporting infrastructure, and we are working with the private sector to address these gaps.

Where is tourism investment currently flowing in Zambia, and which segments are showing the strongest momentum?

Private tourism investment is mainly going into lodges and hotels, particularly around national parks, while MICE is also growing quickly.

A major opportunity is a modern, large-scale conference facility in Livingstone, which could strengthen Zambia’s position as a meetings and conventions destination and attract delegates combining business with leisure.

In Lusaka, demand for hotel rooms increasingly exceeds supply during major conferences and international events, creating opportunities for larger hotels and quality accommodation. The government is also preparing amendments to the Tourism and Hospitality Act, expected to be tabled in the next Parliament after the elections, to bring platforms such as Airbnb into the formal tourism sector through standards and regulation.

What is one of the most significant untapped investment opportunities in Zambia’s tourism sector today?

Kazungula stands out, where Zambia, Botswana, Namibia and Zimbabwe converge around the Zambezi River. The area offers potential for hotels, restaurants and waterfront attractions, while its location at the region’s quadripointgives it a distinctive proposition for tourism investment.

What are the main challenges investors should consider when entering Zambia’s tourism sector, and how is the government addressing them?

The main challenges are transport infrastructure, reliable electricity and development within or near protected areas, particularly in remote tourism locations.

Poor roads can increase construction costs, while Zambia’s 752,614 square kilometres, with about 30% reserved for wildlife, can create challenges involving land encroachment and community engagement.

The government is addressing these through Community-Based Natural Resource Management (CBNRM), ensuring communities participate in and benefit from tourism, while promoting solar and other renewable energy solutions in areas with limited grid access.

How is Zambia leveraging digital tools and technology to enhance its visibility and competitiveness in international markets?

Digital marketing is central to our tourism strategy. Through the Zambia Tourism Agency (ZTA), we worked with Paul Charles to target five priority markets: the UK, Germany, France, Italy and the United States. The campaign surpassed its target of 1 billion online impressions, reaching more than 1.4 billion views.

We also work with Booking.com, Expedia and the BBC, while online visas, digital payments and booking platforms are making travel to Zambia more accessible.

How has domestic tourism performed in terms of volume and its contribution to sector stability?

Domestic tourism grew from 235,000 visitors in 2021 to 562,000 in 2025. The “Take a Holiday Yamu Loko” campaign has encouraged Zambians to explore their own country, with participating lodges offering 20% to 50% discounts.

Why should Zambia be considered a priority tourism destination for international visitors and investors compared with other African markets?

Zambia combines exceptional wildlife, diverse tourism experiences and strong investment potential. Liuwa Plain National Park hosts Africa’s second-largest wildebeest migration, while Kasanka National Park is home to the world’s largest migration of straw-coloured fruit bats, from October to December. The Kavango-Zambezi (KAZA) Transfrontier Conservation Area supports one of Africa’s largest elephant populations, while South Luangwa has Zambia’s highest concentration of hippos and crocodiles.

For investors, Zambia offers a pro-business, private sector-led economy, a liberal foreign-exchange regime and 100% repatriation of net profits, with opportunities across tourism, mining, agriculture and other strategic sectors. The newly launched “Zambia Moves You” campaign brings the country’s tourism and investment opportunities, natural resources and people under one international identity.


Jordan Extends Industrial Incentives as Ma’an Package Targets Manufacturing Costs

Jordan Extends Industrial Incentives as Ma’an Package Targets Manufacturing Costs

Jordan is extending incentives for industrial estates in Madaba, Salt and Tafileh for another three years and has approved a broader package for the Al Rawdah Industrial City in Ma’an, as the government seeks to attract manufacturing investment outside the capital and tie public support more closely to production, employment and local value creation.

The measures come as Jordan continues to adjust its investment framework under the Economic Modernisation Vision, with the government seeking to improve the operating environment for investors while directing more economic activity towards the governorates.

Jordan’s Minister of Investment, Dr. Tareq Abu Ghazaleh, said in a Jordan TV interview that the three-year extension is intended to give viable projects that have been delayed by market conditions, regional crises and other challenges more time to complete construction and enter production. Eligibility remains linked to actual project implementation, the employment of Jordanian workers and the creation of industrial value added, according to Petra.

The three industrial estates had attracted 105 companies and more than JD162 million in investment by the end of June, Abu Ghazaleh said, with the minister putting employment generated at more than 3,400 jobs.

A separate statement from the Jordan Industrial Estates Company, however, reported more than 1,640 jobs across the three estates. The differing figures should be read with care, as the two government sources do not explain whether they are using different employment definitions or reporting bases. JIEC said the estates had occupancy rates of 40%, up from 27.5%, while investments were distributed across Madaba, Salt and Tafileh.

Ma’an package focuses on operating costs

The more extensive package is aimed at Al Rawdah Industrial City in Ma’an, where the government is offering incentives covering some of the principal costs facing manufacturers during the early years of operation.

According to the Ministry of Investment, the package provides electricity-cost support for five years. The government will cover 75% of electricity costs during the first two years, 50% during the next two years and 25% in the fifth year.

Companies will also be eligible for support for employing workers from the local area for up to three years, including contributions towards wages, social security payments and transportation costs. For export-oriented manufacturers, the government will subsidise 50% of container-handling costs at Aqaba Port for three years.

Land is another component of the package. Industrial plots covering more than 20 dunums will be priced at JD7.5 per square metre, compared with JD15 previously, subject to a maximum total area of 120 dunums, according to the Ministry of Investment.

For investors, the combination is notable because it addresses several upfront and operating costs at the same time. Energy prices, land expenditure, labour costs and export logistics can have a material effect on the economics of a manufacturing project, particularly during the ramp-up period.

Incentives linked to investment performance

The support is not unconditional. Projects seeking the Al Rawdah incentives must begin operations within the required timeframe, achieve at least 30% local value added and meet minimum employment requirements for residents of the governorate, according to the Ministry of Investment.

The Cabinet has also limited access to the wider industrial-estate incentive programme in Madaba, Tafileh and Salt to up to 15 companies per estate, according to the Jordan Times’ report on the Cabinet decision. The newspaper also reported that the programme will continue to be financed through an existing government grant rather than creating an additional burden on the Treasury.

That performance-based approach is important from an investment-policy perspective. Rather than treating incentives simply as a reduction in project costs, Jordan is linking access to measurable outcomes such as operational start-up, employment and domestic value creation.

Part of wider investment reforms

The industrial measures form part of a broader effort to update Jordan’s investment framework. The Ministry of Investment said the amended Investment Environment Regulation for 2026 was published in the Official Gazette on June 4, with the changes aimed at improving the investment environment, streamlining procedures and supporting investment attraction and job creation.

The government has also been using incentives to encourage investment in governorates rather than concentrating activity in Amman. The Ministry said the Al Rawdah package followed Prime Minister Jaafar Hassan’s visit to Ma’an and subsequent directives concerning the needs of investors and local communities.

For international manufacturers, the policy shift presents an opportunity but also leaves practical questions for due diligence. The value of the incentives will ultimately depend on infrastructure availability, energy reliability, workforce availability, logistics costs and the speed with which projects can move from approvals and construction into commercial production.

Jordan’s government is effectively testing whether targeted incentives can convert industrial land and development zones into productive manufacturing capacity. The performance of the projects receiving support — measured in factories entering production, capital deployed, jobs created and local value generated — will determine whether the strategy succeeds in attracting longer-term industrial investment to the country’s governorates.

Estonia Cuts Investment Grant Threshold as It Targets More Industrial Projects

Estonia Cuts Investment Grant Threshold as It Targets More Industrial Projects

Estonia is expanding access to its largest investment support programme by lowering the minimum qualifying investment from €100 million to €70 million, a move aimed at attracting a wider range of industrial, technology and strategic manufacturing projects.

The revised criteria were introduced through the updated large-scale investment grant guidelines published by Enterprise Estonia (EIS), the government agency responsible for supporting business development and investment activity. The changes are designed to make the scheme accessible to more companies while continuing to prioritise investments that strengthen exports, productivity and economic value creation.

Under the amended framework, companies no longer need to commit to projects exceeding €100 million to qualify. The lower threshold allows more medium-to-large industrial investments to enter the programme, particularly in sectors identified as strategically important for Estonia’s economy.

The revised rules also introduce different entry points depending on the type of investment. According to EIS, priority development projects can qualify with eligible costs from €35 million, while defence-related industrial projects can enter the scheme from €20 million.

Food manufacturing has also been added to the programme’s priority sectors, expanding the scope beyond technology-focused industries. Other eligible areas include net-zero technologies, the decarbonisation of energy-intensive industries, critical raw materials processing, strategic digital technologies, deep technology and biotechnology.

Lower Employment Requirement Broadens Access

Alongside the reduced investment threshold, Estonia has lowered the minimum job creation requirement for supported projects.

Companies applying under the scheme must now create at least 20 new positions, compared with the previous requirement of 30 jobs. The adjustment is intended to reflect the changing nature of modern industrial investments, where projects in areas such as automation, advanced manufacturing and technology development may require significant capital investment but fewer employees than traditional factories.

The Estonian government has linked the programme to its broader objective of attracting investments that generate long-term economic benefits, including higher-value employment, increased exports and stronger industrial capacity.

Grants Cover Up to 15% of Eligible Investment

The investment support available through the programme remains capped at €20 million per project.

According to the EIS guidance, companies investing in Harju County can receive support of up to 10% of the investment value, while projects located elsewhere in Estonia may qualify for grants of up to 15%.

Applicants must finance at least 85% of the investment themselves, ensuring that public funding supports projects with significant private-sector commitment.

The structure of the scheme is aimed at supporting major investments without replacing private capital, with grants focused on projects expected to deliver measurable economic impact.

Focus on Industrial Capacity and Strategic Sectors

The changes come as European economies compete to attract investment into sectors linked to energy transition, digitalisation and supply-chain resilience.

For Estonia, the updated programme provides a targeted incentive mechanism for companies considering new production facilities, technology centres or industrial expansion. Rather than offering broad-based incentives, the scheme links public support to specific investment outcomes, including export growth, innovation and employment creation.

The inclusion of food manufacturing alongside advanced technology sectors also reflects an effort to strengthen domestic production capacity and reduce vulnerabilities in key supply chains.

Companies Must Pass Investment Assessment Process

Businesses seeking support must meet eligibility requirements established by EIS, including registration in the Estonian Commercial Register and compliance with ownership, investment and employment conditions.

Before submitting an application, companies are required to complete a preliminary consultation and assessment process. Applications are then submitted through Estonia’s electronic funding platform, E-toetus.

EIS evaluates projects based on several factors, including economic impact, implementation capacity, project readiness, the quality of employment created and the location of the investment.

For companies evaluating expansion opportunities in Europe, the revised grant programme lowers the initial investment barrier while maintaining a focus on projects that contribute to Estonia’s industrial development, export capacity and technological competitiveness.

Côte d’Ivoire’s Baleine Development Advances as Saipem Wins Major Offshore Infrastructure Contract

Côte d’Ivoire’s Baleine Development Advances as Saipem Wins Major Offshore Infrastructure Contract

Côte d’Ivoire’s offshore energy sector is set for further expansion after Italian engineering group Saipem secured a major contract linked to the next phase of development at the Baleine oil and gas field, strengthening one of West Africa’s most significant recent energy projects.

According to Saipem’s announcement on 27 July 2026, the company was awarded two contracts by Eni and its subsidiaries with a combined value of approximately €800 million. One of the agreements covers subsea infrastructure for Baleine Phase 3 offshore Côte d’Ivoire, while the second relates to the expansion of renewable fuel production capacity at Eni’s biorefinery in Italy.

The Baleine Phase 3 contract was awarded by Eni Côte d’Ivoire and its partners and will involve the engineering, fabrication, transportation and installation of key subsea facilities required for the continued development of the field.

Saipem will be responsible for installing offshore infrastructure including pipelines, subsea production equipment, flexible connections and export systems. The project will take place in deep waters reaching approximately 1,300 metres and is expected to run for around three years, according to the company.

The development builds on the growing importance of the Baleine discovery, which has become a central element of Côte d’Ivoire’s strategy to expand domestic oil and gas production and strengthen energy security.

Discovered in 2021 by Eni and Côte d’Ivoire’s national oil company PETROCI, Baleine is considered one of the largest hydrocarbon discoveries in the country’s history. The field entered production in 2023, with subsequent development phases designed to increase output and expand the contribution of local gas resources to the economy.

For Côte d’Ivoire, increased gas availability has wider economic implications beyond the energy sector. Additional domestic supply can support electricity generation, industrial activity and efforts to attract investment into energy-intensive sectors.

The Saipem award also comes as African oil and gas producers continue to seek investment in infrastructure that can unlock natural resources while supporting economic transformation. Offshore projects require significant technical expertise and long-term capital commitments, making partnerships with international engineering companies a critical component of resource development.

Alongside the Côte d’Ivoire project, Saipem announced a separate contract from Enilive, Eni’s energy transition subsidiary, for the construction of a new processing unit at its Venice biorefinery.

The facility will support increased production of hydrotreated vegetable oil (HVO), a renewable fuel produced from biological feedstocks. Saipem said the project forms part of its broader cooperation with Eni in developing biofuel infrastructure.

Together, the two contracts highlight the changing nature of the global energy industry, where traditional oil and gas developments are increasingly taking place alongside investments in lower-carbon technologies.

For Côte d’Ivoire, the next phase of Baleine represents more than an offshore development project. It reflects the country’s broader effort to use energy resources as a foundation for industrial growth, improved energy reliability and increased participation in regional energy markets.

As West Africa’s economies compete for investment in energy infrastructure, projects that combine resource development with economic linkages are likely to remain central to attracting long-term capital.