Friday, October 16, 2026
No menu items!
Home Blog Page 22

Uganda Unveils Digital Transformation Roadmap to Propel Technological Progress

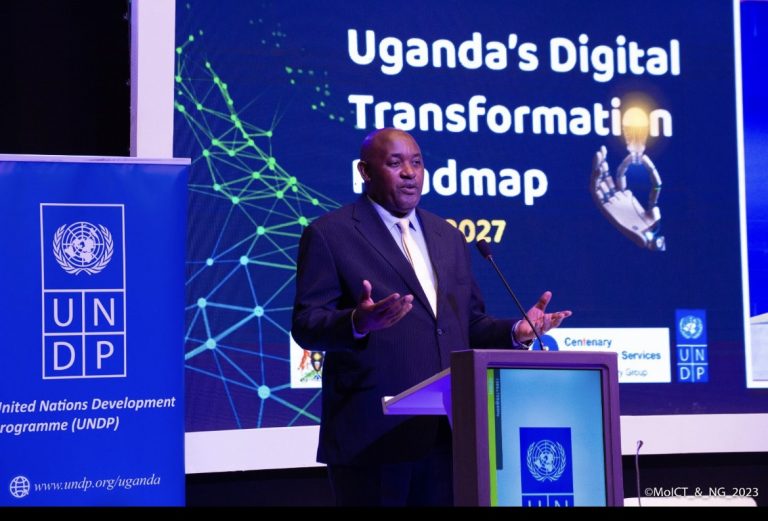
On the 17th of August, a significant stride was taken towards Uganda’s digital evolution as the Ministry of ICT and National Guidance (MoICT&NG), in collaboration with the United Nations Development Programme (UNDP), introduced the much-anticipated “Digital Transformation Roadmap for Uganda.” This roadmap stands as a pivotal implementation tool aimed at realizing the objectives of the Digital Uganda Vision, propelling the nation into a digitally connected and prosperous future.

The newly unveiled Digital Transformation Roadmap serves as a blueprint for executing enabling policies and laws that will propel Uganda’s Digital Revolution forward. This strategic framework sets the stage for a well-connected Uganda, poised to harness the opportunities offered by a myriad of cutting-edge technologies.

Uganda’s Information and Communication Technology (ICT) sector has emerged as a formidable force, contributing significantly to the nation’s Gross Domestic Product (GDP). With a notable 9% share of the total GDP, this sector has not only bolstered the country’s revenue but has also provided livelihoods to approximately 2.3 million individuals. This remarkable achievement can be attributed to a collaborative effort between the Government and private entities, encompassing initiatives spanning from expanding infrastructure coverage to developing diverse e-services.

While the field of information and communication services has maintained an average growth rate of 14.8%, it is worth noting that segments like computer programming, ICT trade, and manufacturing have shown comparatively modest contributions to overall growth.

Uganda’s Digital Transformation Roadmap

Digital Uganda Vision 2040: Aligned with Uganda’s ambitions to transition from an agrarian society to a modern, prosperous nation within the next three decades, the Government, guided by the Ministry of ICT and National Guidance, introduced the Digital Uganda Vision (DUV). This visionary strategy aims to empower Uganda digitally through a meticulously crafted roadmap. The development of the DUV took into account a spectrum of national cyber-related laws, regulations, policies, and strategies, drawing from sources like the NRM Manifesto, post-2014 ICT-related laws, Uganda Vision 2040, and National Development Plan III.

Notably, the DUV seamlessly integrates with global, continental, and regional commitments. This integration encompasses progress towards the Sustainable Development Goals, the Africa Agenda 2063, and the East Africa Vision 2050.

Pillars of Digital Transformation: Central to the Digital Uganda Vision are five foundational pillars that guide Uganda’s trajectory towards becoming a modern and prosperous nation by 2040:

  1. Digital Infrastructure and Connectivity: Establishing an integrated digital infrastructure to meet present and future demands, enhancing nationwide digital connectivity.
  2. Digital Services: Focusing on delivering information and data across platforms, this pillar drives the development and implementation of citizen-centric e-services.
  3. Cybersecurity and Data Protection: Ensuring secure digital environments and safeguarding personal data against unauthorized access.
  4. Digital Skills: Emphasizing digital literacy, skill development, and workforce readiness for emerging technologies.
  5. Innovations and Entrepreneurship: Stimulating local ICT enterprises and commercializing indigenous innovations.

Navigating the Digital Transformation Roadmap: The Digital Transformation Roadmap serves as the operational guide that translates the Digital Uganda Vision into action. Aligned with each pillar, this roadmap outlines specific interventions aimed at achieving the vision’s goals. It spotlights key areas, from enhancing digital infrastructure to expanding e-services, bolstering cybersecurity, and nurturing digital skills.

Addressing challenges and limitations across domains such as internet penetration, broadband coverage, cybersecurity safeguards, and industry skills, the roadmap envisions a digitally empowered society with significant outcomes anticipated within the designated timeframe.

Looking Ahead: The Digital Transformation Roadmap paints a promising picture of Uganda’s role in the global digital economy. With steadfast progress across diverse indices, Uganda is poised to secure its position in the digital age. The full Digital Transformation Roadmap document is accessible for further exploration: Uganda Digital Transformation Roadmap.
Accelerating Uganda’s Industrial Vision: Insights from the 4th Bi-Annual CEO Retreat

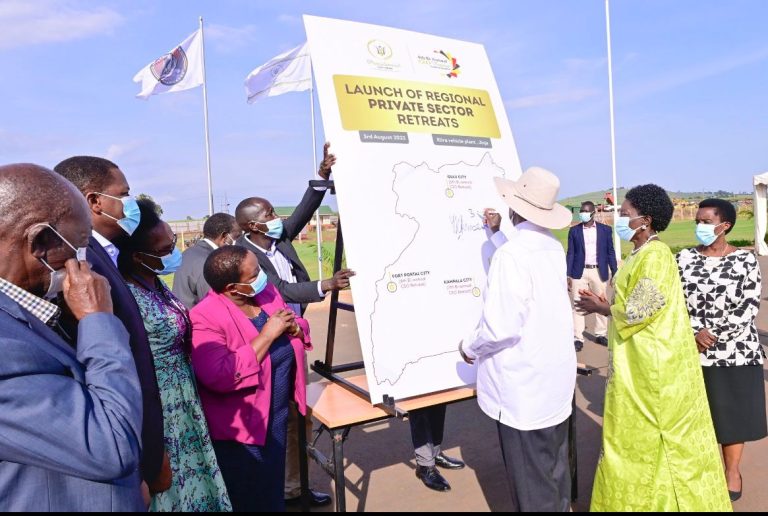
Jinja, Uganda – The 4th Bi-Annual CEO Retreat, skillfully organized by the Presidential CEO Forum (PCF), concluded with resounding success, bringing together influential stakeholders to delve into Uganda’s industrialization agenda. Themed ‘Uganda’s Industrialisation Agenda: Positioning Uganda as a net source of E-Mobility Solutions in Africa,’ the CEOs gathered to reflect on achievements and plan for the future. The retreat, held at the illustrious Kiira Vehicle plant in Jinja, provided an exclusive platform for participants to explore the vast potential for transformative growth in the country’s industrial sector.

Picture Credits: PCF

At its core, the retreat highlighted the impressive Kiira Motors Vehicle plant, showcasing state-of-the-art facilities that will encompass an Assembly Shop, Plant Offices, Power and Water Distribution Systems, Waste Management Facilities, Perimeter Fence and Gate Facilities, Drainage System, and Whole Vehicle Test Facilities. This cutting-edge infrastructure undeniably reflects Uganda’s unwavering commitment to nurturing a robust e-mobility sector.

A pivotal focus of the retreat was the plant’s aspiration to source 90% of its components locally, symbolizing Uganda’s strategic emphasis on indigenous procurement. Prioritizing domestic sourcing is expected to stimulate value addition and unlock the full growth potential of the burgeoning e-mobility sector. This forward-thinking approach is set to bolster the nation’s economy, propel job creation, and establish a self-reliant and sustainable manufacturing ecosystem.

During the retreat, President Museveni made significant announcements, disclosing visionary plans for the establishment of two new cement factories in the Karamoja region, facilitated by a private company. These factories hold transformative potential, not only in cement production but also as crucial hubs for clinker manufacturing, a vital raw material in cement production. Currently, Uganda heavily relies on clinker imports from UAE, Kenya, and India, as evidenced by Volza’s Uganda Import data, which recorded imports reaching 1.8K. The decision to establish these factories aligns seamlessly with Uganda’s overarching vision of reducing reliance on foreign sources and fostering self-sufficiency.

Beyond its industrialization focus, the distinguished Presidential CEO Forum (PCF) Retreat cultivated an atmosphere of collaboration and dedication, uniting both the government and private sector in purpose. This synergy among participants lays a robust foundation for a transformative journey towards sustainable economic growth and technological advancement.

UAE Unveils New Federal Ministry of Investment to Enhance Economic Strategy and Global Competitiveness

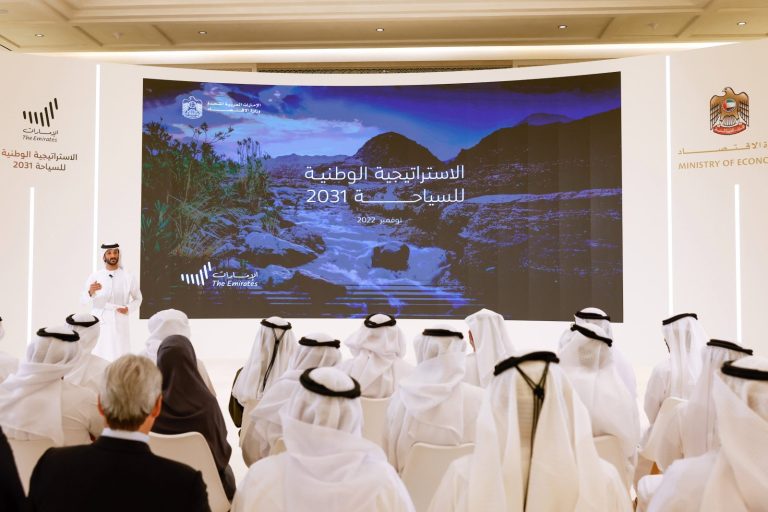
The United Arab Emirates (UAE) has revealed plans to establish a new federal ministry of investment aimed at developing the country’s investment strategy both domestically and globally. This initiative comes in response to increasing economic competition from neighboring nations in the Gulf region.

As Gulf states heavily rely on revenue from hydrocarbons, they are actively seeking ways to diversify their economies and income sources. Among the Gulf states, the UAE is considered one of the most advanced, having successfully developed sectors such as financial services and tourism. The country has also implemented crucial social and business reforms to attract foreign investment.

Sheikh Mohammed chairs the Cabinet meeting at Al Watan Palace in Abu Dhabi. Photo credit: Gulf Today, Staff Reporter

Sheikh Mohammed bin Rashid al-Maktoum, the UAE’s prime minister and ruler of Dubai, took to Twitter to announce the plans after a cabinet meeting. He further shared that Mohammed Hassan Al Suwaidi would assume the role of investment minister, although no additional details were provided at this time.

The objectives of the new ministry include stimulating the investment environment within the UAE and making legislative and procedural enhancements to increase competitiveness in attracting global investment. Additionally, the UAE will establish a Financial Stability Council to monitor risks and effectively handle financial crises, aligning with its goal of becoming a prominent global financial center.

Earlier this year, Sheikh Mohammed launched an ambitious 10-year economic plan called D33, which aims to double the size of the UAE’s economy and establish Dubai as one of the world’s top four financial centers within a decade.

According to the 2022 Financial Times “fDi Markets” report, Dubai attracted an estimated $12.8 billion in foreign direct investment capital in the previous year. In comparison, Saudi Arabia received approximately 30 billion riyals ($8 billion) in foreign direct investment, based on data from the Saudi investment ministry.

Furthermore, the UAE cabinet has approved an updated national energy strategy, highlighting the government’s commitment to energy security and sustainability.

These initiatives, including the establishment of the new federal ministry of investment, underscore the UAE’s determination to maintain its position as a leader in economic diversification, global investment attraction, and financial stability within the Gulf region

Kenya and European Union Sign Landmark Trade Deal to Strengthen Economic Ties

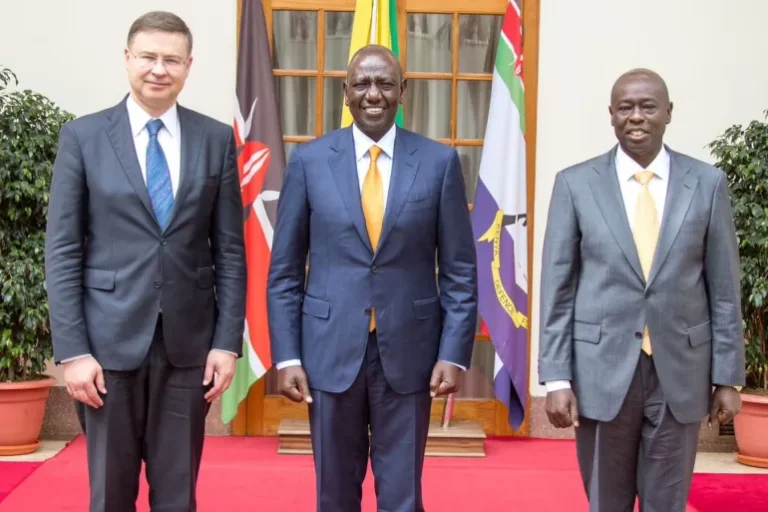
In a significant development for Brussels’ quest to deepen economic engagement with Africa amidst competition from China, Kenya and the European Union have signed a trade deal. Kenyan President William Ruto presided over a ceremony in Nairobi to mark the formal conclusion of negotiations for the EU-Kenya Economic Partnership Agreement.

Once ratified and implemented, the agreement will grant Kenya duty-free and quota-free access to the EU, its largest market, which currently receives approximately one-fifth of all Kenyan exports. The deal will also lead to progressive tariff reductions over 25 years for EU imports to Kenya, except for some sensitive products.

Kenyan Trade Minister Moses Kuria expressed pride in the momentous occasion, highlighting the significance for both Kenya and the European Union. Kenya’s main exports to the EU include agricultural products like vegetables, fruits, tea, and coffee. Furthermore, more than 70% of Kenya’s cut flowers find their destination in Europe.

President Ruto emphasized that the deal would assure a predictable market for Kenyan farmers and provide new opportunities to boost trade. For Kenyan industrialists, it ensures a stable market, while EU industrialists also stand to benefit.

EU Trade Commissioner Valdis Dombrovskis highlighted the strong appetite among EU companies to expand business in Kenya, which has already received 1 billion euros ($1.1bn) in investments over the past decade. This trade deal will serve as a catalyst for further collaboration.

The agreement marks the first comprehensive trade deal between the EU and an African nation since 2016. It comes as a response to China’s Belt and Road program, with the EU announcing increased investments in Kenya through its Global Gateway initiative.

Dombrovskis sees Kenya as a beacon of dynamism and opportunity in a region often characterized by turbulence. The EU views Africa as a priority region and hopes this agreement with Kenya will pave the way for stronger trade ties across the continent.

The trade deal is the culmination of a decade-long negotiation process between the EU and the East African Community (EAC), which initially included Kenya, Rwanda, Uganda, Burundi, and Tanzania. Kenya proceeded independently in ratifying the agreement, but Dombrovskis stated that the deal remains open for other EAC members, including the Democratic Republic of the Congo and South Sudan, to join.

European Commission Gives Green Light to €21 Billion Microelectronics Project

The European Commission has officially approved the second Important Project of Common European Interest (IPCEI) for microelectronics, with a budget of €21 billion. This project will focus on energy-efficient technologies and encompass 68 individual projects, spanning a wide range of areas from sensors to 5G and automotive technology. The main objective of the IPCEI is to develop groundbreaking solutions and drive innovation in Europe’s microelectronics industry.

By fostering research, development, and production capabilities in the chip sector, the project aims to address the challenges posed by the green and digital transitions. It is projected that the IPCEI will generate approximately 8,700 highly skilled jobs, contributing to the growth and competitiveness of Europe’s microelectronics sector.

This approval comes as a follow-up to the success of the first IPCEI agreed upon in 2018. The previous IPCEI resulted in significant advancements in microelectronics, particularly witnessed in Germany and Austria, where the expansion of Infineon and Bosch fabs in Dresden, as well as sub-10nm lithography optics from Carl Zeiss, took place.

The European Commission’s decision to greenlight the IPCEI signifies a commitment to enhancing Europe’s own research, development, and production capabilities in the microelectronics industry. State aid will be provided to companies involved in the projects, including the establishment of joint ventures and the construction of new facilities.

In addition to the IPCEI, the European Union has implemented other measures to support the microelectronics sector. Notably, the European Chips Act focuses on research, development, and innovation support, bridging the gap between research and production and streamlining procedures for the construction of wafer fabs and assembly plants.

The IPCEI was jointly prepared and notified by 14 member states, including Austria, France, Germany, Italy, and Spain. These member states will contribute up to €8.1 billion in public funding, expected to leverage an additional €13.7 billion of private investments. A total of 56 companies, encompassing small and medium-sized enterprises as well as startups, are involved in the IPCEI, making it the largest of its kind among the six approved in the region thus far.

The approved IPCEI aims to drive research and development in innovative and resource-efficient technologies and components, such as chips, processors, and sensors, which can be integrated into various applications and industries. The project is organized into four interconnected workstreams: “Sense” focuses on novel sensors, “Think” on processors and memory chips, “Act” on efficient and high-performance components, and “Communicate” on rapid and secure communication technologies.

The European Commission ensures that the proposed public support for the IPCEI is appropriate and limited to the necessary amount. A claw-back mechanism has been put in place, requiring large beneficiaries to return part of the aid received if their projects exceed profitability expectations. Furthermore, the Commission emphasizes the importance of sharing the innovative results beyond the participating companies and countries, promoting conferences, publications, access to facilities, testing kits, and licensing of intellectual property rights.

The European Commission is actively collaborating with member states on four upcoming IPCEIs, focusing on health, cloud, hydrogen, and other key technologies. These initiatives aim to support innovation, cooperation, and economic growth within the European Union

OPEC+ Member Countries Agree to 40.46 Million bpd Output Target from 2024; Saudi Arabia Extends Voluntary Cut


In a significant development, member countries of OPEC+ have come to a consensus on a new output target of 40.46 million barrels per day (bpd) beginning in 2024. The agreement, outlined in a statement issued by the group, reflects their collective commitment to maintaining stability in the oil market.

Alongside this decision, Saudi Arabia’s energy ministry has announced the extension of its voluntary production cut of 500,000 bpd until the end of December 2024. This extension, coordinated with select OPEC+ participants, follows discussions held during the recent OPEC+ meeting.

OPEC+ showcases its collective determination to effectively manage oil production

OPEC+ showcases its collective determination to effectively manage oil production

Additionally, the ministry has revealed an additional voluntary reduction of 1 million bpd for the month of July, with the possibility of further extensions. Consequently, Saudi Arabia’s production will be adjusted to 9 million bpd, resulting in a total voluntary cut of 1.5 million bpd throughout July, according to reports from the Saudi Press Agency.

The ministry has emphasized that this supplementary voluntary cut is a proactive measure aimed at supporting the precautionary efforts of OPEC+ member countries in maintaining oil market stability and equilibrium.

By establishing the new output target and extending the voluntary cut, OPEC+ showcases its collective determination to effectively manage oil production levels and address evolving market dynamics.

African Development Fund Approves $3.9M Grant to Upgrade Liberia’s Payments Infrastructure

0

The African Development Fund’s Board of Directors recently gave the green light to a $3.9 million grant aimed at bolstering Liberia’s payments infrastructure and systems project. The grant, provided through the Bank’s concessional lending window, was approved on March 17. The primary objective of the project is to enhance Liberia’s payments ecosystem, fostering growth, innovation, and increased efficiency. Specifically, the project will focus on upgrading the automated cheque processing and automated clearing house (ACP/ACH) systems, as well as the real-time gross settlement (RTGS) system, which serve as the backbone of payment processing in Liberia’s financial sector.

The project will also entail the modernization of the Central Bank of Liberia’s main data center and disaster recovery sites. This endeavor is expected to have a positive impact on the Central Bank, government ministries involved in payments, commercial banks, and their customers. Ultimately, all stakeholders will benefit from improved services, faster processing times, real-time transactions, and online administrative access.

The implementation of the project is scheduled to commence in June 2023.

Central Bank of Liberia

Furthermore, the project will contribute to increased inclusion and regional integration through the implementation of technological upgrades that meet the required standards. This initiative holds particular significance for Liberia as it will directly support the deployment of the proposed National Electronic Payments Switch (NEPS) system, which focuses on the retail market where financial exclusion is most pronounced. With the NEPS project already approved by the World Bank in 2022 and currently underway, the additional project is crucial for improving financial inclusion in Liberia, which currently stands at 44.2% (Findex 2021). Its aim is to extend access to underserved populations, including youth, women, smallholder farmers, Micro, Small, and Medium Enterprises (MSMEs), and rural communities.

The implementation of the project is scheduled to commence in June 2023 and will be carried out in close collaboration between the Central Bank of Liberia and banking and non-banking institutions.

Benedict Kanu, the African Development Bank country manager for Liberia, emphasized the significance of modernizing Liberia’s payments infrastructure and systems. He highlighted the positive ripple effects it will have on the formal financial sector, including increased financial stability and improved private sector development. Kanu further noted that these improvements will contribute to narrowing the financial inclusion gap by providing essential infrastructure support for the World Bank-financed NEPS project. Additionally, the project will position Liberia to participate in the region’s financial integration efforts and facilitate increased cross-border trade, both of which necessitate a robust payments infrastructure.

Ahmed Attout, acting director for the Financial Sector Development Department, underlined the Bank’s financial sector development strategy, which aims to support domestic financial systems in regional member countries and ensure compliance with regional and international financial standards. He stressed the critical role of financial sector development, infrastructure provision, and digital finance support in driving private sector growth, particularly in an increasingly digital world that demands greater inclusivity.

Liberia’s financial sector faces several challenges, including inadequate ICT infrastructure and limited coverage in remote areas. While the existing payments infrastructure, established with the assistance of the African Development Bank in 2016, has served the country well over the past six years, it requires urgent upgrades. This project is poised to maximize the potential for strengthening the financial sector, promoting financial stability, bridging the gap in financial inclusion, and facilitating regional integration

UAE and Republic of Peru Strengthen Bilateral Ties with Air Services Agreement


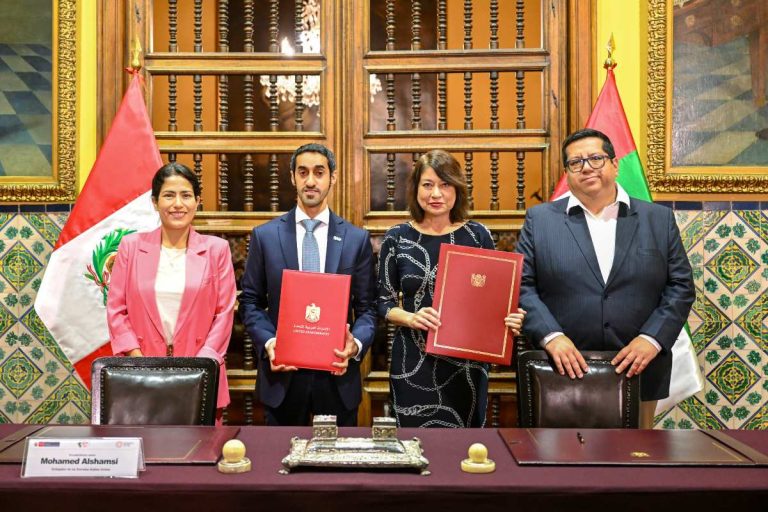
The United Arab Emirates (UAE) and the Republic of Peru have solidified their partnership with the signing of an air services agreement. The agreement was formalized by Mohammed Abdullah Al Shamsi, UAE Ambassador to the Republic of Peru, on behalf of the UAE, and Gervasi Díaz, Minister of Foreign Affairs, representing Peru.

This milestone agreement marks a new chapter in the cooperation between the two nations and is set to enhance intra-trade and foster collaboration across various sectors. Al Shamsi highlighted that the non-oil bilateral trade between the UAE and Peru reached US$800 million in 2022, while UAE investments in Peru surpassed US$700 million over the past five years. Additionally, the intra-trade volume during the same period amounted to US$4.4 billion.

This milestone agreement marks a new chapter in the cooperation between the two nations.

An airplane moments from touching down on the runway at sunrise. Getty Images Image used for illustrative purpose.

Al Shamsi also emphasized the importance of previous agreements, such as the Memorandum of Understanding for political consultations in 2009 and the visa waiver agreement in 2019. With the signing of the air services agreement, both countries are looking forward to future collaborations, including agreements to protect and promote investments, avoid double taxation, and other initiatives that align with their mutual goals for development and prosperity.

The ambassador stressed that this agreement will facilitate increased trade exchange, support the economic agendas of both nations and strengthen aviation ties. It will benefit national airlines and various sectors, directly impacting the growth of air traffic between UAE and Peru’s airports, ultimately bolstering trade, economic, and tourism relations.

In response, Minister Díaz emphasized the UAE’s significance as Peru’s largest Arab investor, underlining the historic nature of this air services agreement as the first between the Middle East and South America. She highlighted the agreement’s potential for Peru to serve as a communication hub for airline networks in Latin America. Díaz deemed the signing of the agreement as a significant achievement and a pivotal moment in the robust relations between Peru and the UAE.

Díaz further noted that the agreement will pave the way for the establishment of new air routes, promoting tourism and business travel between Peru, and Arab countries, as well as Asian and Pacific nations.

Africa Finance Corporation and Morocco’s Ministry of Economy and Finance Join Forces for Infrastructure Development


Africa Finance Corporation (AFC), the leading provider of infrastructure solutions in Africa, and Morocco’s Ministry of Economy and Finance have entered into a strategic partnership. This collaboration, solidified through a Memorandum of Understanding (MOU), aims to accelerate the development of key strategic sectors, including renewable energy, transport, natural resources, heavy industries, and telecommunications.

The MOU signifies an important milestone in the growing relationship between AFC and Morocco, following Morocco’s official membership in the AFC in 2021. By leveraging AFC’s expertise in project development, structuring, and financing, this partnership seeks to provide innovative solutions that will enhance Morocco’s infrastructure and industrial base. These improvements are crucial for fostering domestic market competitiveness and expanding the export capacity of Moroccan businesses.

AFC is currently engaged in high-level discussions with various government entities in Morocco.

Morocco, Africa Finance Corporation Partner to Boost Critical Financing for Local Institutions

Over the past decade, Morocco has actively pursued opportunities in sub-Saharan Africa, and its renewed membership in the African Union reflects its commitment to becoming a major contributor and leader in Africa’s economic development. The partnership with AFC represents another significant step towards realizing this vision, aiming to create a vibrant economic region in Africa characterized by increased intra-Africa trade, job creation, political stability, and economic prosperity.

H.E Nadia Fettah, Moroccan Minister of Economy and Finance, expressed the importance of this collaboration, stating, “This marks a major step in the cooperation between Morocco and the AFC and confirms the continuous commitment of the Kingdom of Morocco to Africa’s development, in line with the vision of His Majesty the King, in promoting South-South cooperation.”

AFC is currently engaged in high-level discussions with various government entities in Morocco, including the Ministry of Transportation & Logistics, the National Railway Operator, the Airport Authority, and the Ministry of Energy Transition & Sustainable Development. Among the projects being considered are the revitalization and enhancement of significant railway infrastructure to improve mobility of passengers and cargo between rural towns and the capital city, as well as collaboration under Morocco’s renewable energy strategy. These initiatives reflect Morocco’s dedication to sustainable development and the transformation of its infrastructure landscape.

US-India State Visit: A Crucial Step Towards Stronger Bilateral Relations and Economic Partnerships


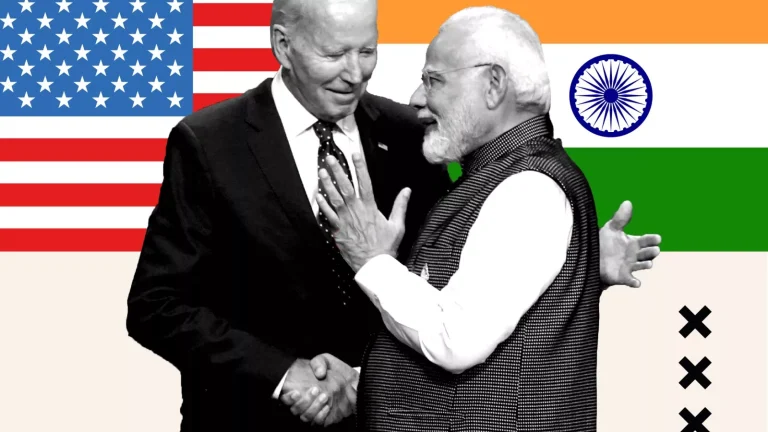
The State Visit of Prime Minister Narendra Modi, at the invitation of President Joe Biden, marks a significant moment in the relationship between the United States and India. Atul Keshap, President of the US-India Business Council (USIBC), recognizes the importance of this visit in shaping the future of both countries.

Keshap emphasizes the rarity and prestige of State Visits between the United States and India, with this being only the third occurrence in their diplomatic history. This visit serves as a powerful symbol of the strong bond and close friendship between the two nations.

This visit serves as a powerful symbol of the strong bond and close friendship between the two nations.

USA-INDIA Flags

Anticipating the visit, Keshap expresses optimism about the impact on various sectors, including strategic, economic, and technological collaborations. He highlights the potential for enhanced trade, increased investment, and the strengthening of bilateral relations in key industries such as energy, semiconductors, digital economy, and defense.

Keshap also underlines the importance of a robust defense industry, emphasizing that collaboration between American and Indian companies in this field will contribute to deterrence and ensure peace and security. He announces a unique initiative, the “wedding mela,” which aims to foster partnerships between defense startup enterprises from both nations.

Furthermore, Keshap emphasizes the significance of treating American companies fairly and equally, providing them with predictability and a level playing field when doing business. He acknowledges that Indian companies also value favorable conditions for investment in the United States.

Overall, the State Visit of Prime Minister Modi signifies a momentous occasion for strengthening ties, promoting trade, and fostering collaboration between the United States and India across various sectors.